Independent opinions of value for office, industrial and warehouse, multifamily and retail property — developed to USPAP standards for financing, acquisition, disposition, financial reporting, property-tax and litigation purposes.
An appraisal answers one question: what is a defined property interest worth, as of a defined effective date, for a defined intended use. That is a different question from the one a market report answers. A market report explains how a market is performing — rents, vacancy, absorption, concessions, competitive supply and comparable sale evidence across a property type or geography. An appraisal applies recognised valuation methodology to a single subject property and reaches a supported conclusion of value. Market research is frequently an input to an appraisal, but a market report is not itself an appraisal and does not constitute an opinion of value.
A property appraisal and an acquisition business valuation serve different purposes; compare their SBA context in the SBA valuation and underwriting guide.
Wert-Berater performs both disciplines and keeps them in separate engagements, with separate scope, separate deliverables and separate fees. Where a transaction needs both, the market research and the appraisal can be coordinated so that the valuation assignment draws on current primary market evidence rather than stale secondary data.
Single-tenant and multi-tenant office, medical office and flex office. Analysis addresses market rent by class and submarket, vacancy and availability including sublease space, concession and free-rent packages, operating-expense structures and recovery methods, lease rollover exposure, and comparable sale evidence including price per square foot and capitalisation-rate indications where the data support them.
Distribution, warehouse, light manufacturing and flex industrial. Building characteristics drive value in this class — clear height, column spacing, dock and drive-in configuration, trailer parking, power, office finish ratio and site coverage — alongside market rent, availability, absorption, land sale evidence and functional or economic obsolescence.
Conventional and affordable apartment property and build-to-rent communities. Analysis addresses asking and effective rents, rent per unit and per square foot, occupancy and physical vacancy, concessions, unit mix and amenity positioning, lease-up performance where applicable, operating-expense trends and reserves, and comparable apartment sales expressed per unit and per square foot.
Shopping centres, grocery-anchored and neighbourhood centres, strip retail, single-tenant net-lease property and owner-occupied retail. Requirements differ materially among these formats — anchor strength, tenant mix, lease structure and term, trade-area demand and competing retail nodes all bear on the income analysis and on the selection of comparable evidence.
Property whose value depends on an operating business — hotels, healthcare and senior-living facilities, entertainment venues and special-purpose plants — is handled under Special-Purpose & Going-Concern Appraisal, where the real estate, the business enterprise and the tangible personal property are valued and allocated as one integrated assignment.
Closed sales of competing property, adjusted for location, physical characteristics, condition, market conditions at the date of sale and the property rights conveyed. The reliability of this approach depends on the depth and comparability of the available evidence, which is stated in the report rather than assumed.
Direct capitalisation and, where the assignment warrants it, discounted cash flow. Inputs — market rent, vacancy and collection loss, operating expenses, reserves, lease-up and rollover assumptions, capitalisation and discount rates — are supported from market evidence and disclosed, so that a reviewer can test them.
Replacement or reproduction cost less depreciation, plus land value. Applied where it is relevant to the assignment — newer improvements, thin sale evidence, insurance or financial-reporting purposes, or where physical, functional and external obsolescence need to be measured explicitly.
Highest and best use is tested as vacant and as improved against what is legally permissible, physically possible, financially feasible and maximally productive. The approaches applied are then reconciled into a single conclusion, with the weight given to each explained.
The income capitalization approach measures the present value of the future benefits associated with ownership of an income-producing property. It is often central to an office appraisal, retail appraisal, industrial or warehouse appraisal, and multifamily appraisal because buyers in those markets commonly compare assets through income, yield and risk. The appraiser reconstructs the subject’s operating history, reviews current leases and rent rolls, and develops market-supported assumptions rather than accepting a budget at face value. Contract rent, market rent, reimbursements, vacancy, collection loss, operating expenses, reserves, lease rollover and capital obligations are considered in the format market participants use for the property type.
The approach may be applied through direct capitalization, discounted cash flow analysis, or both. The choice depends on the stability of the income stream, lease structure, expected changes in occupancy and expenses, and the way comparable properties are bought and sold. Under USPAP, the scope of work must be sufficient for the intended use and the property being appraised; no single technique is automatically required in every assignment.
Direct capitalization converts one year of stabilized net operating income into value through a market-derived overall capitalization rate. The selected income year should represent the property’s expected ongoing performance, not simply the latest historical year or the owner’s next budget. The appraiser normalizes atypical items, brings below- or above-market income to an appropriate basis where warranted, and distinguishes operating expenses from debt service, depreciation, income tax and capital expenditures.
The basic relationship is value equals net operating income divided by the capitalization rate, but the analysis behind each term is the substantive work. The capitalization rate must be consistent with the income definition and timing. Comparable-sale extraction, investor surveys and band-of-investment or mortgage-equity techniques may inform the conclusion, with their relevance and limitations explained.
A discounted cash flow analysis forecasts periodic cash flows over an explicit holding period and discounts them, together with the anticipated reversion, to present value. It is useful where lease rollover, tenant improvements, leasing commissions, free rent, changing occupancy, phased renovation or other events make one stabilized year an incomplete description of the property. For a multi-tenant office valuation or shopping-center valuation, tenant-by-tenant lease events may materially affect both timing and risk. Industrial properties with a single near-term rollover can require similar treatment.
The DCF states the forecast period, inflation or growth assumptions, market-rent changes, renewal probability, downtime, concessions, capital costs and terminal-value method. A terminal capitalization rate is applied to an appropriately defined forward income measure, and selling costs are recognized. The result is tested against alternative holding periods and key assumptions rather than presented as precision unsupported by the evidence.
The sales comparison approach develops an indication of value from transactions involving reasonably similar properties. Comparable sales are verified where practicable and analyzed for property rights conveyed, financing terms, conditions of sale, expenditures immediately after purchase, market conditions, location and physical and economic characteristics. Adjustments may be quantitative or qualitative depending on the depth and reliability of market evidence.
Units of comparison follow market behavior: price per square foot for many office, retail and industrial properties; price per unit for multifamily; and price per acre or square foot for land appraisal. Occupancy, lease term, tenant credit, building quality, age, condition, clear height, parking, site coverage and development potential can all affect comparability. The report explains why each sale was selected and how conflicting indications were resolved.
The cost approach estimates land value as though vacant, adds the current cost to construct improvements of equivalent utility, and deducts depreciation. Replacement cost and reproduction cost are distinguished. Direct and indirect costs, entrepreneurial incentive and the effective date of the appraisal are considered. Depreciation may include physical deterioration, functional obsolescence and external obsolescence; these are economic conclusions, not merely age-based deductions.
This approach can be particularly relevant for newer property, proposed construction, insurance-related intended uses, special building features or markets with limited comparable sales. It may receive less weight where an older property has difficult-to-measure obsolescence or buyers focus predominantly on income. Land value is supported separately through comparable land sales or another appropriate land valuation method.
Market rent analysis compares the subject’s space with competing leases on the terms market participants actually negotiate. The review distinguishes asking rent from executed rent and records lease type, expense responsibility, term, escalation, tenant-improvement allowance, leasing commission, free rent and other concessions. Differences in location, building class, floor, size, condition, access, parking and amenities are considered. Effective rent provides a common basis when nominal rents carry different concession or expense packages.
Contract rent is then compared with market rent by tenant or unit type. That comparison informs renewal assumptions, rollover risk and any above- or below-market position relevant to the property interest appraised. Office, retail, warehouse and multifamily properties require different comparable criteria; a generic metropolitan average is not a substitute for submarket and product-specific evidence.
Highest and best use is analyzed as though the land were vacant and, when improved, as the property exists. Reasonably probable uses are tested in order for legal permissibility, physical possibility, financial feasibility and maximal productivity. Zoning, land-use controls, access, utilities, site characteristics, market demand, development cost and return all bear on the conclusion. Existing improvements are retained only if their contribution supports the indicated use; renovation, conversion, expansion or redevelopment may warrant consideration.
This analysis supports the value opinion within the appraisal. A broader consulting assignment that ranks multiple development programs is distinct; owners still choosing among uses can review the firm’s highest and best use study consultant service. Where storage is the selected concept but market support and lease-up remain the open questions, a self storage feasibility analysis is a separate feasibility engagement and not an appraisal.
Vacancy and collection loss is developed from the subject’s history, current occupancy, lease expirations, submarket vacancy and availability, tenant demand, new supply and the performance of competing properties. Physical vacancy, economic vacancy and collection loss are distinguished. A fully leased building may still carry economic loss through concessions, nonpayment, below-market rent or expected downtime at rollover.
The stabilized allowance should reflect the expected experience over a holding period rather than conditions on one inspection date. Tenant concentration, credit, rollover schedule and speculative space influence the conclusion. For multifamily valuation the analysis also considers concessions, bad debt, employee or model units and loss-to-lease; for office and retail it may require explicit downtime and renewal probability by suite.
Expense analysis reviews several years of operating statements when available and compares the subject with market benchmarks on a per-square-foot, per-unit and percentage-of-income basis as appropriate. Real estate taxes, insurance, utilities, payroll, management, repairs and maintenance, contract services, administrative expense and reserves are considered separately. Recoveries are matched to lease obligations so reimbursed expenses are not counted without the corresponding cost.
Historical anomalies and owner-specific costs are identified, but normalization is evidence-based. Deferred maintenance may require a deduction or capital forecast rather than an artificially high recurring expense. Management expense is recognized at a market level even for an owner-managed property when market participants would account for that service.
Capitalization rate analysis begins with comparable investment sales for which price and forward income can be aligned. Extracted rates are interpreted in light of location, property quality, occupancy, tenant credit, remaining lease term, growth expectations and capital needs. A sale involving durable long-term income does not carry the same risk as a partially vacant asset merely because the buildings share a property type.
Investor surveys can provide context, while band-of-investment and debt-coverage methods can test the relationship among financing, equity return and property income. These sources are reconciled rather than averaged mechanically. The selected rate is tied to the same net operating income definition used in direct capitalization.
The discount rate in a DCF represents the yield required for the forecast cash flows and their associated risk. Evidence may include investor surveys, comparable transactions, market participant interviews and return relationships observed in financing and capital markets. The rate is considered alongside the terminal capitalization rate, growth assumptions and the degree to which risk has already been reflected in the cash-flow forecast.
Nominal cash flows require a nominal discount rate, and the timing convention must be consistent throughout the model. Sensitivity tests show how the value indication changes with reasonable movements in the discount rate, terminal rate, rent growth, vacancy and capital costs. This makes the effect of uncertain assumptions visible to the intended user.
Reconciliation is the reasoned process of weighing the quality and relevance of the data and methods used. It is not a simple average of the cost, sales comparison and income indications. An approach supported by numerous verified transactions and market-aligned assumptions may deserve substantial weight; an approach dependent on sparse sales or uncertain depreciation may provide only a secondary check. The property type, property interest, intended use and behavior of typical buyers guide that weighting.
The appraisal report explains the reliability of each approach, resolves material differences and states the final market value conclusion as of the effective date. The appraiser also identifies extraordinary assumptions or hypothetical conditions where applicable and communicates the assignment results in a manner that is not misleading. Development and reporting are performed under USPAP and applicable state appraisal requirements, with the signed certification and scope tailored to the assignment.
Common intended uses include acquisition and disposition decisions, refinance, collateral underwriting, partnership and shareholder matters, financial reporting, property-tax matters, litigation and dispute resolution, highest-and-best-use questions, and workout or distressed-asset analysis.
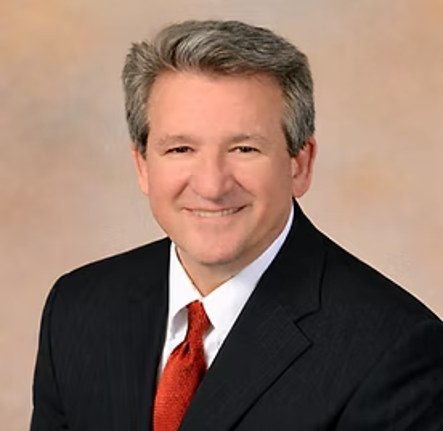
Wert-Berater’s Senior Valuation Advisor holds the MAI designation from the Appraisal Institute, where he has been a member since 2006, and the ASA-GC (Going Concern) designation from the American Society of Appraisers. He is also a Business Certified Appraiser (BCA) and a Certified Machinery/Equipment Appraiser (CMEA). He maintains Certified General real estate appraiser licenses in New Jersey, New York, Pennsylvania, Maryland and Virginia, and has appraisal experience in at least 25 states. He is a staff member of Wert-Berater, Inc. and is also the owner of Special Purpose Realty Valuation.
Special Purpose Realty Valuation — 402 Birmingham Avenue, Manchester, NJ 08759 · (732) 374-9064. That is Mr. Jones’s own firm; it is not a Wert-Berater, Inc. office.
These designations and licenses are held personally by Bruce E. Jones. The analysts who prepare Wert-Berater market reports and feasibility studies do not hold these appraisal designations and do not sign appraisal reports.
Where a lender, owner or counsel needs the market context behind the numbers, our custom market reports can be commissioned alongside — or independently of — an appraisal assignment: office market analysis, industrial and warehouse market reports, multifamily market analysis, retail market reports, gas station and truck stop market analysis, hospital and ASC market reports. These reports analyse the market. They are not appraisals and do not state an opinion of value.
If you are still deciding which engagement a transaction needs, Feasibility Study vs. Appraisal sets out the distinction in more detail.
No. A market report analyzes supply, demand, competition and market conditions for a property type or geography. An appraisal develops an opinion of value for a specific property or property interest as of a defined effective date and for an identified intended use. A transaction may require one or both, and they are separate engagements with separate deliverables.
This service covers conventional income-producing commercial real estate: office buildings, industrial and warehouse property, multifamily and apartment property, and retail property. Property whose value depends on an operating business, such as hotels, fuel and travel centers, healthcare facilities and special-purpose plants, is handled under our special-purpose and going-concern appraisal service, which addresses the real estate, the business enterprise and the tangible personal property as an integrated assignment.
Bruce E. Jones holds Certified General real estate appraiser licenses in New Jersey, New York, Pennsylvania, Maryland and Virginia, and has appraisal experience in at least 25 states. Assignments outside the states of licensure are completed in accordance with applicable state appraiser licensing and temporary practice requirements. Because those requirements vary by state, jurisdiction is confirmed before an assignment is accepted.
Yes. Appraisal assignments are developed to the Uniform Standards of Professional Appraisal Practice. The scope of work, the interest appraised, the definition of value, the effective date and the intended use and intended users are established in writing at engagement, and conclusions are never contingent on a predetermined outcome or on the amount of the value opinion.
No. An appraisal is developed for an identified intended use and identified intended users, and it is not automatically suitable for a different purpose. An appraisal prepared for collateral underwriting, for example, may not be appropriate for financial reporting or for a property-tax appeal. If the intended use changes, the assignment generally needs to be re-scoped.
Appraisal fees are separately scoped and quoted based on the property, the intended use, the effective date, the jurisdiction and the assignment requirements. Fees are not contingent on the value reported, on a predetermined result, or on the occurrence of a subsequent event. Appraisal is not sold as a fixed-price product and is not included in any market-report package.
Legal disclosure. Wert-Berater, Inc. offices are mailing addresses only. Following the COVID-19 pandemic the firm has elected to work remotely; its office locations receive mail and are not staffed for visitors or in-person meetings. Headquarters mailing address: 1968 South Coast Hwy, Ste 2382, Laguna Beach, CA 92651.
Wert-Berater, Inc. is an independent provider of feasibility studies and other related services. The firm does not provide financing or equity investment advice, and does not arrange, broker, or place debt or equity capital of any kind.
All appraisal assignments are performed by Bruce E. Jones, MAI, ASA-GC, BCA, CMEA, a member of the Appraisal Institute since 2006, a staff member of Wert-Berater, Inc. and owner of Special Purpose Realty Valuation.
Thousands of real estate, business, and machinery appraisal and litigation assignments.
Analytical continuity
Connect the capital decision to actual asset and portfolio performance.
The analytical relationship does not have to end when the feasibility study is delivered. Wert-Berater can continue monitoring the asset against the original underwriting assumptions, updating market conditions, testing coverage, identifying performance variances and maintaining a recurring analytical record.