
Testimony and litigation-support valuation for operational properties where value is derived from the integrated performance of real estate, business operations, and personal property — the assignments conventional appraisal alone cannot resolve.
Wert-Berater provides testimony and litigation-support services for matters involving operational properties whose value comes from the integrated performance of the real estate, the business operating within it, and the tangible personal property that makes it run. These are precisely the assignments where conventional real estate methodology, applied alone, falls short — and where the allocation between real property, business enterprise value, and equipment becomes the central question in dispute.
Full-service and convention hospitality, where going-concern value, FF&E, and business enterprise value must be properly segregated from the underlying real estate.
Operating businesses with significant intangible and personal-property components, liquor licenses, and event-driven income streams.
Special-purpose plants where machinery, equipment, and process improvements are inseparable from the real estate’s productive value.
Destination and experiential properties combining land, hospitality, production, and brand into a single going concern.
For these property types, the question is rarely just “what is the real estate worth.” It is how much of the total value belongs to the real estate, how much to the business operating within it, and how much to the tangible personal property — and whether those components have been allocated correctly under USPAP. Getting that allocation wrong is what drives property-tax disputes, partnership and shareholder disagreements, lending and workout litigation, condemnation matters, and damages claims. Our work emphasizes credible, well-supported, and defensible conclusions in exactly the assignments where conventional real estate methodologies alone are insufficient.
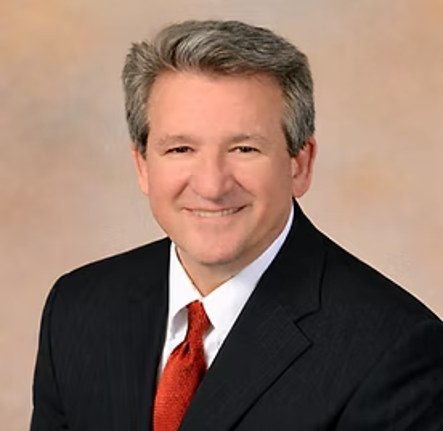
Wert-Berater’s Senior Valuation Advisor holds the MAI designation from the Appraisal Institute, where he has been a member since 2006, and the ASA-GC (Going Concern) designation from the American Society of Appraisers — one of the few credentials specifically focused on complex valuation assignments involving business enterprise value. He is also a Business Certified Appraiser (BCA) and a Certified Machinery/Equipment Appraiser (CMEA), allowing the firm to deliver a fully integrated valuation across every component of value in a single, reconciled analysis.
In real estate since 1987, he specializes in special-purpose, operational property — hotels, restaurants, gas stations, car washes, funeral homes, and the many other property types that sell as a combination of real estate, an intangible business value component, and tangible non-real-estate assets. The ASA Going-Concern specialty is designed for appraisers who regularly appraise complex commercial real estate with a business component and who understand when — and when not — to allocate or segregate the value components and analyze their effect on value as USPAP requires. The BCA and CMEA designations are each recognized by the U.S. Small Business Administration as a “Qualified Source” for business and equipment appraisals.
Bruce E. Jones, MAI, ASA-GC, BCA, CMEA serves as Wert-Berater’s Senior Valuation Advisor, a staff member of the firm who is also owner of Special Purpose Realty Valuation. Availability for any specific assignment is confirmed in writing and is subject to a conflicts check and a signed retainer.
We are regularly retained as an expert in litigation and property-tax-appeal matters, particularly those involving:
Separating real property, business enterprise value, and tangible personal property in operating assets — the allocation that most disputes turn on.
Quantifying how much of total value is attributable to the real estate versus the business operating within it, with a defensible, USPAP-consistent methodology.
Large-scale resort, convention, and institutional properties where the analysis must withstand sophisticated cross-examination.
Contested HBU analysis for assemblages, transitional uses, and special-purpose assets with limited comparable evidence.
Recent expert-witness engagements include large-scale resort and convention properties in the Orlando market, including assets affiliated with major global hospitality operators. Property-tax-appeal testimony has involved the Waldorf Astoria Orlando; Disney’s Yacht & Beach Club Resort; Disney’s Coronado Springs Resort; Disney’s Pop Century & Art of Animation Resorts; and Disney’s Wilderness Lodge. Beyond testimony, the breadth of special-purpose assignments behind these opinions includes:
Assignments above are representative of the expert’s body of work across his career and are listed to illustrate depth in special-purpose and going-concern valuation; they are not a claim of engagement by every named property’s current ownership.
The same discipline that holds up under cross-examination is what makes Wert-Berater valuable before a matter ever reaches dispute. For complicated projects, we build the analysis that complex, multi-component assets actually require — not a single cap-rate applied to a one-dimensional comparable set. For distressed situations and workouts, we provide independent restructure-extend-liquidate analysis, orderly and forced-liquidation values, and re-underwritten market evidence that is committee-ready and litigation-durable. And for special-purpose properties — the operational assets most appraisers avoid — the firm’s integrated real estate, business, and equipment competency means a single reconciled opinion rather than three disconnected ones. Whether the goal is financing, a workout, a tax appeal, or testimony, the standard of evidence is the same.
Our role is to help counsel, owners, and stakeholders understand complex issues through disciplined analysis, clear scope definition, and well-supported conclusions. Each engagement begins with a focused understanding of the dispute, followed by targeted research and structured analysis designed to withstand scrutiny in mediation, arbitration, or court proceedings. Clients rely on us for consistent quality, clear communication, and an unwavering commitment to objectivity throughout the litigation process.
A going-concern valuation prepared for litigation or dispute resolution is not a standard feasibility study with a cover letter attached. The scope is built around the specific questions the trier of fact must answer: what was the property worth, what was it capable of earning, and on what evidence does that conclusion rest. For hotels, resorts, marinas, golf courses, assisted-living facilities, and other special-purpose assets, that means the analyst must reconstruct the operating platform—not merely the real estate—because the business enterprise value, the FF&E, and the real property interest are legally and economically distinct components that courts and arbitrators treat separately.
Demand analysis for a hotel, resort, marina, or other experience-driven asset cannot be assembled from a single database pull. The analyst must identify who the customer is, where that customer comes from, and what alternatives existed at the relevant date of value—because opposing counsel will challenge every assumption that lacks a traceable source.
For lodging assets, primary sources include STR historical performance data, state tourism office visitation records, convention and visitors bureau reports, and air-traffic statistics from the relevant gateway airports. For marinas and waterfront facilities, slip-registry data, state boating registration records, and Army Corps of Engineers permit files establish both existing supply and pipeline. For senior-housing and care facilities, state licensing registries, certificate-of-need filings, and Medicare cost reports provide the competitive inventory. For golf and resort amenity assets, National Golf Foundation market studies and local permit records document supply-side changes over time.
Competitive-supply work requires more than a radius search. Each comparable property is evaluated on its demand segmentation, its flag or brand affiliation if any, its physical condition at the relevant date, and its pricing tier. Properties that opened, closed, or changed flag during the dispute period are identified and their effect on the subject's performance is isolated. The result is a demand conclusion that can be defended line by line under cross-examination.
In any discounted-cash-flow or income-capitalization model, a small number of inputs carry the weight of the conclusion. For special-purpose, going-concern assets in litigation, identifying those inputs—and showing exactly how they were tested—is the difference between an opinion a court credits and one it disregards.
SBA, USDA, and conventional lenders each bring a distinct analytical lens to complex, special-purpose assets, and that lens sharpens considerably when the asset is the subject of litigation, a buyout dispute, a bankruptcy proceeding, or a condemnation action.
Under SBA SOP 50 10 8, the lender must document that projected cash flow covers debt service at a minimum 1.15x operating coverage and 1.00x global coverage. When the asset is a hotel, resort, or other going concern, the SBA lender must also satisfy itself that the going-concern value—not merely the real estate value—supports the loan amount. An independent study that separates those value components and tests them under stress gives the lender the documented basis the SOP requires.
USDA Business & Industry and Community Facilities programs under RD Staff Instruction 5001 impose similar coverage disciplines and additionally require that the analyst demonstrate market need. For a rural resort, marina, or senior-care facility, that means showing that the demand base is durable, not dependent on a single employer or seasonal event.
Conventional lenders typically require 1.20x coverage and place particular weight on the stabilization timeline—how many months before the asset reaches the occupancy or utilization level the model assumes. A litigation-support engagement prepared to these standards gives the lender a document it can present to its credit committee without restatement.
A fixed fee is quoted within one business day of receiving a complete description of the asset, the dispute, the date of value, and the scope of the opinion required. The fee does not change based on the conclusion reached, and no portion of it is contingent on the outcome of the litigation or the transaction. That structure is not incidental: it is the foundation of the independence that makes the opinion defensible.
The engagement begins with a defined data room. For a complex going-concern asset, that room typically includes historical operating statements for a minimum of three years, the most recent property-condition assessment, any existing appraisals or prior feasibility studies, franchise or management agreements, and the relevant legal filings that define the scope of the dispute. The analyst will identify missing items before work begins rather than issue a qualified opinion after delivery.
Standard delivery is ten to fifteen business days from a complete data room. Rush delivery is available when court deadlines require it. The finished report is a bound narrative with all supporting schedules. The fully linked Excel model is published to a secure client portal where it remains live: any input can be changed and the model recalculates in real time, which means counsel, the opposing expert, or the court's own consultant can stress any assumption without requesting a revised report. Conditions that bound the opinion are stated explicitly in the report and are not revised under pressure from any party.
The fee is fixed and quoted within one business day of receiving a complete description of the asset, the dispute, and the scope of the opinion required. It does not vary with the conclusion and no portion is contingent on the outcome. Because scope varies significantly by asset complexity and date-of-value requirements, a specific quote requires a brief intake conversation.
Standard delivery is ten to fifteen business days from receipt of a complete data room. Rush delivery is available when court or arbitration deadlines require a shorter window. The timeline begins when the data room is complete, not when the engagement is signed, so early identification of missing documents is a priority in every engagement.
A hotel or resort generates income through an operating business, not a lease. That means the analyst must separately value the real property, the FF&E, and the intangible business value—components that move independently and that courts treat as legally distinct. Occupancy, rate, and expense assumptions are all operator-dependent, which means every input requires independent support rather than a simple rent-roll review.
The underlying analysis often overlaps, but the standard of value, the date of value, and the scope of the opinion differ between a lending engagement and a litigation engagement. A report prepared for SBA underwriting is built to SOP 50 10 8 coverage standards; a litigation report is built to the evidentiary requirements of the proceeding. Attempting to repurpose one for the other without restating scope creates credibility risk under cross-examination.
At minimum: three or more years of historical operating statements, a current or recent property-condition assessment, any existing appraisals or prior feasibility studies, franchise or management agreements in effect at the date of value, and the legal filings or dispute documents that define the scope of the opinion. Missing items are identified before work begins so the opinion is not qualified after delivery.
A licensed appraisal establishes market value under USPAP. An expert-witness going-concern valuation may use income, cost, and sales-comparison methods but is scoped specifically to the questions at issue in the dispute—which may include component allocation, historical earning capacity, or the effect of a specific event on value. The two products are complementary but are not interchangeable in a litigation or arbitration context.
Tell us a little about your project and what you’d like to see. We’ll set up a short private walkthrough of the portal, monitoring, or both — conducted by our team — and confirm a time by email or phone within one business day, with a Zoom link to follow.
Sign in to your live portal to open your model, review your study, and track performance against the original projections — 24/7.
Sign in to your portal →Legal disclosure. Wert-Berater, Inc. offices are mailing addresses only. Following the COVID-19 pandemic the firm has elected to work remotely; its office locations receive mail and are not staffed for visitors or in-person meetings. Headquarters mailing address: 1968 South Coast Hwy, Ste 2382, Laguna Beach, CA 92651.
Wert-Berater, Inc. is an independent provider of feasibility studies and other related services. The firm does not provide financing or equity investment advice, and does not arrange, broker, or place debt or equity capital of any kind.
All appraisal assignments are performed by Bruce E. Jones, MAI, ASA-GC, BCA, CMEA, a member of the Appraisal Institute since 2006, a staff member of Wert-Berater, Inc. and owner of Special Purpose Realty Valuation.